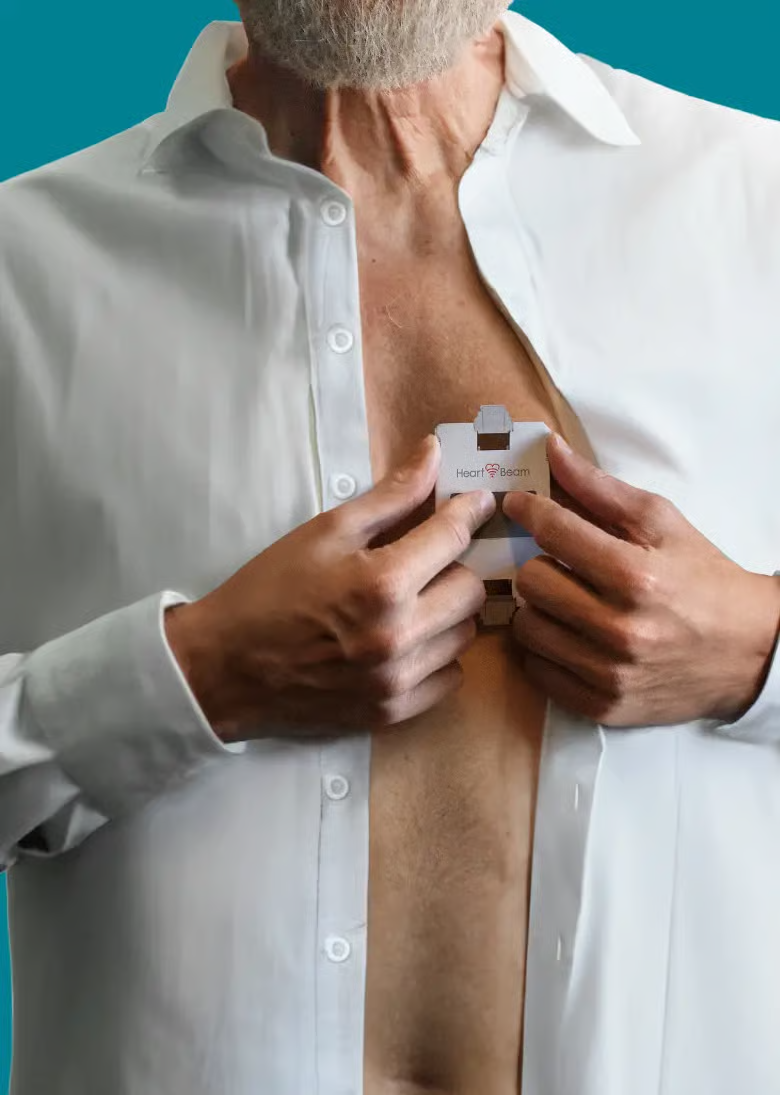
Bridging the Last Mile of Acute Cardiology: Synthesized 3D Vectorcardiography at Home
 Dr. Dereck Mush, MD, MBA
Press release · Company announcement
Berg Insight
23 October 2026
Gothenburg, Sweden – October 22, 2026: Berg Insight today released new findings on the mHealth market. The number of connected home medical monitoring devices reached 92.7 million worldwide in 2025 as the market acceptance continues to grow in several key verticals. This number includes all connected medical devices used by patients enrolled in mHealth care programmes as part of the care regimen. Connected medical devices used for various forms of personal health tracking are not included in this figure. Berg Insight forecasts that the number of connected home medical monitoring devices will grow at a compound annual growth rate (CAGR) of 11.5 percent to reach 159.7 million by 2030.
The three main applications are remote monitoring and management of sleep therapy devices, diabetes management and remote monitoring of patients with implantable cardiac rhythm management (CRM) devices. Sleep therapy is by far the most connected segment and is dominated by ResMed. Additional vendors include Philips, BMC Medical, Löwenstein Medical Technology. The number of monitored patients continues to grow and has more than doubled since 2018, largely due to the compliance monitoring requirements that have been introduced in the US and Europe. Glucose level monitoring and insulin delivery has grown significantly in the last years and is now the second largest segment with 19.5 million connections at the end of 2025. The growth is driven by the increased adoption of continuous glucose monitoring (CGM) systems and insulin delivery systems from leading providers such as Abbott, Dexcom, Insulet, Tandem Diabetes Care and MiniMed. The CRM market is led by companies such as Medtronic, Abbott, Boston Scientific and BIOTRONIK that started to include connectivity in CRM solutions more than two decades ago. Other categories include remote ECG monitoring, telehealth, medication compliance, blood pressure monitoring and other connected care applications. The fastest growing market segments in the next five years are anticipated to be diabetes management, remote ECG monitoring and medication compliance monitoring. Today, the leading connected healthcare players in these segments include forward-thinking incumbents as well as innovative new entrants such as AliveCor, Bardy Diagnostics, Boston Scientific, Biotricity, Compliance Meds Technologies, Dignio, Evondos, Philips, Dexcom, Glooko, GE Healthcare, Hero Health, Insulet, iRhythm Technologies, InfoBionic.Ai, MedMinder, MedReady, Medtronic, MiniMed, Roche, Tandem Diabetes Care, WellDoc and Withings.
mHealth software and services are one of the most rapidly developing parts of the mHealth value chain. This segment includes platforms and software solutions that enable remote patient monitoring by utilizing connected devices like wearables and sensors to collect vital signs data and health metrics in real-time. Service providers in this space offer comprehensive solutions that integrate data analytics, telehealth capabilities and patient engagement tools to ensure continuous and efficient care. Companies that specialise in this area include Amwell, Aptar Digital Health, Alira Health (Bepatient), CareSimple, Doccla, Huma Therapeutics, Omron Healthcare (Luscii), Medisanté, MedM, S3 Connected Health, Current Health, SHL Telemedicine, Teladoc Health, Tellihealth, TytoCare, Enovation (Legrand Care), Vivalink and Welldoc.
The focus is increasingly moving from episodic care towards continuous monitoring and proactive intervention. Healthcare providers are adopting remote and home-based care models to improve patient outcomes, reduce avoidable hospitalisations and readmissions, manage healthcare costs and extend access to specialist care. Healthcare systems around the world have undergone a transformation driven by an ageing population, rising healthcare costs and changing patient needs. The market is shifting towards a connected, decentralised and patient-centric model of care. Healthcare industry players have responded to this by developing connected medical devices, expanding remote patient monitoring programmes and integrating digital health platforms that enable providers to monitor patients remotely. Self-engagement apps and compliance monitoring solutions ensure that patients adhere to prescribed treatments, enhancing the effectiveness of medical regimens. Digital health solutions can indeed help ease the burden of an already strained healthcare sector by improving access to patient data, increasing efficiency and supporting better quality of care. The market is today moving beyond standalone connected devices towards integrated solutions that combine hardware, software and data analytics to support more efficient and personalised care”, says Vatsala Raina, IoT Analyst at Berg Insight. Artificial intelligence (AI) has advanced significantly, analysing large datasets and aiding in disease diagnostics and management. “AI and machine learning accelerate the shift towards remote and home-based care by identifying early signs of patient deterioration, supporting timely interventions and enabling healthcare providers to manage patients more effectively outside traditional clinical settings”, concludes Mrs. Raina.
About Berg Insight Berg Insight is a dedicated M2M/IoT market research firm based in Sweden. We have been specialising in all major M2M/IoT verticals such as fleet management, car telematics, smart metering, smart homes, mHealth and industrial M2M since 2004. Our vision is to be the most valuable source of intelligence for our customers. Berg Insight offers numerous market reports, detailed market forecast databases and advisory services. We provide custom research tailored to your requirements including focussed research papers, business case analysis, go-to-market strategies and bespoke market forecasting. We have provided analytical services to 1600 clients in 78 countries on six continents to date. Our customers range from many of the world’s largest mobile operators, IT companies and telecom vendors, to venture capitalists, technology start-ups and specialist consultants.
Dr. Dereck Mush, MD, MBAThe HealthTech Signal
The Top Remote Patient Monitoring Platforms of 2026
Dr. Dereck Mush, MD, MBA Dr. Dereck Mush, MD, MBA
 Dr. Dereck Mush, MD, MBA
Keep exploring